
Home buyer programs in Ontario can make buying your first property more affordable, whether you’re saving for a down payment, seeking financial assistance, or preparing for closing costs.
For prospective buyers in Kingston, Frontenac County, Lennox & Addington, and Leeds & Grenville, understanding the available assistance can make a meaningful difference. From tax-free savings accounts and land transfer tax refunds to local down payment assistance, these programs offer several ways to ease the financial challenges of homeownership.
While new construction attracts attention because of government rebates, many first-time buyers will find more realistic opportunities among established homes, townhouses, condominiums, and properties needing improvements.
This guide explains how home buyer programs work, who may qualify, and how to combine available benefits when planning your purchase.
Who Qualifies for Home Buyer Programs in Ontario?
Before exploring the available assistance, it’s important to understand that government programs don’t all use the same definition of a first-time home buyer.
Some benefits require that you have never owned a home anywhere in the world. Others allow people who previously owned property to qualify again after a specified period without living in a home they owned.
Your spouse’s or common-law partner’s ownership history may also affect eligibility.
For example, an individual who owned a property several years ago might qualify for the First Home Savings Account or RRSP Home Buyers’ Plan but not Ontario’s land transfer tax refund.
Similarly, municipal down payment assistance often has its own income, asset, residency, and property-price requirements.
That’s why you should investigate each program separately rather than assume that qualifying for one means you’ll qualify for the others.
The Financial Consumer Agency of Canada’s guide to buying a home offers useful information about preparing financially for homeownership.
First Home Savings Account: Building Your Down Payment
The First Home Savings Account (FHSA) is one of the most useful financial tools for eligible Canadians preparing to buy their first property.
Introduced in 2023, the FHSA combines the advantages of Registered Retirement Savings Plans (RRSPs) and Tax-Free Savings Accounts (TFSAs).
Eligible individuals can:
- Contribute up to $8,000 annually, subject to available contribution room.
- Contribute up to $40,000 over their lifetime.
- Deduct contributions from taxable income.
- Make qualifying withdrawals, including accumulated investment growth, tax-free toward an eligible home purchase.
If both individuals in a couple qualify, their joint lifetime contributions could total $80,000, plus any investment growth
Unlike withdrawals through the RRSP Home Buyers’ Plan, qualifying FHSA withdrawals do not need to be repaid.
One important detail: contribution room accumulates when you first open an FHSA, not automatically when you turn 18. You can carry forward unused finance room, subject to the program’s limits.
If you’re renting in Kingston and planning to buy a home in the next few years, it might be worth talking to a financial adviser about opening an account early.
The Canada Revenue Agency’s FHSA information explains the eligibility requirements and withdrawal rules.
RRSP Home Buyers’ Plan: Accessing Your Retirement Savings
The federal Home Buyers’ Plan (HBP) lets eligible individuals withdraw money from their RRSPs to buy or build an eligible home.
The maximum withdrawal is $60,000 per individual; should both purchasers qualify, their combined withdrawals could reach $120,000.
Unlike a qualifying FHSA withdrawal, you must eventually repay HBP withdrawals to the RRSP.
The normal repayment period is 15 years. The government has extended temporary repayment relief for eligible first withdrawals made between January 1, 2026, and December 31, 2028.
If someone makes their first withdrawal in 2026, they must start repayments in 2031.
Another advantage is that eligible purchasers may use both an FHSA and the Home Buyers’ Plan toward the same qualifying property.
This flexibility can help buyers with retirement savings who haven’t yet accumulated enough in a separate down payment account.
However, withdrawing retirement funds deserves careful consideration. Money removed from an RRSP no longer earns investment returns in that account until you replace it.
Review the CRA’s Home Buyers’ Plan information before deciding whether this option is right for you.
When comparing home buyer programs, consider both the immediate financial benefits and any future repayment obligations.
Ontario Land Transfer Tax Refund: Save Up to $4,000
When purchasing real estate in Ontario, buyers normally pay provincial land transfer tax.
Qualifying first-time buyers may receive a refund of up to $4,000, reducing the money needed on closing day.
For eligible properties valued at $368,000 or less, the refund can eliminate the provincial land transfer tax.
For more expensive properties, the maximum refund still provides a meaningful reduction.
Consider someone purchasing a $450,000 resale home in Kingston.
The regular Ontario land transfer tax would be $5,475. After applying the maximum first-time buyer refund, the buyer would pay $1,475.
That’s a $4,000 saving that can help with moving costs, legal fees, or necessary improvements.
Eligibility requirements include being at least 18 years old, satisfying the ownership-history and citizenship or permanent-residency rules, and occupying the property as your principal residence within nine months.
Your real estate lawyer can usually arrange the refund during closing.
Kingston, unlike Toronto, does not charge an additional municipal land transfer tax.
Unlike some home buyer programs that help you save for a down payment, this refund directly reduces a closing expense.
For full details, visit the Ontario government’s land transfer tax refund guide.
Federal Home Buyers’ Amount: Income Tax Relief
The federal Home Buyers’ Amount is another benefit available to qualifying purchasers.
Eligible buyers can claim up to $10,000 on their federal income tax return for the year they purchase a qualifying home.
This is a non-refundable tax credit, not a grant or a down payment.
The actual benefit depends on the applicable federal tax credit rate and the purchaser’s tax situation. For the 2026 tax year, a full claim can generally reduce federal income tax payable by up to $1,400.
If two eligible people buy a home together, they may split the claim without exceeding the combined maximum.
While it won’t reduce the amount of money you need on closing day, the credit could provide helpful tax savings once you settle into your new home.
Details are available through the Canada Revenue Agency’s information on the Home Buyers’ Amount.
Among the available home buyer programs, the FHSA is especially useful because it encourages people to save well before they buy.
Home Buyer Programs in Kingston and Frontenac County
Among the local assistance options, the City of Kingston’s Home Ownership Program deserves particular attention.
This program helps eligible lower-income households purchase affordable homes in Kingston or Frontenac County by providing a forgivable loan toward the down payment.
Unlike many national benefits, this assistance targets qualifying local households that need help to enter homeownership.
Under the published program guidelines:
- Eligible homes must cost $500,000 or less.
- Down payment assistance can reach $37,500, subject to program limits.
- The program offers the assistance via an interest-free, forgivable loan.
- The loan has a 20-year forgiveness period.
- Applicants must meet household income, asset, residency, financing, and other requirements.
- The household must occupy the property as its principal residence.
The published income limits are $95,000 for a qualifying one-income household and $130,000 for a qualifying two-income household.
The program also has a $50,000 asset limit, with certain exemptions.
An important distinction involves registered savings. The City excludes RRSPs and certain other registered accounts from its asset calculation, but it includes FHSA and TFSA balances.
For eligible households, this is one of the most valuable local home buyer programs because it addresses the challenge of accumulating a sufficient down payment.
Someone saving diligently for a down payment should therefore examine the City’s rules before assuming they qualify.
Understanding the eligibility requirements for different home buyer programs before you search can help prevent disappointment later
The Importance of Timing in Applications
One of the most significant requirements is that applicants must receive program approval before making an offer to purchase a property.
Making an offer first and applying for assistance afterwards can make a buyer ineligible.
Once approved, buyers have a limited time to locate an eligible property and submit the required purchase documentation.
Resale homes also require a home inspection.
The property serves as security for the assistance. Selling, transferring, or ceasing to occupy the home before the forgiveness period ends may trigger repayment obligations, potentially including a share of the property’s appreciation.
Planning for the Next Application Period
Kingston has closed applications for its 2026 Home Ownership Program because it has reached the available application capacity.
That doesn’t mean prospective purchasers should ignore the program.
People hoping to buy in the future can review the eligibility requirements, organise their finances, and monitor announcements about subsequent funding opportunities.
Avoid assuming future application dates or funding until official confirmation.
Visit the City of Kingston’s affordable housing programs for current details.
Home Buyer Programs in Eastern Ontario
Kingston is not the only place offering homeownership assistance. Other Eastern Ontario communities offer programs that may help purchasers qualify with a down payment.
However, funding availability and program rules can differ substantially.
Leeds & Grenville Homeownership Program
The United Counties of Leeds and Grenville administer a Homeownership Program that offers down payment assistance through an interest-free loan.
The program may forgive the loan after 20 years, as long as the household does not sell the property and it remains their sole residence.
Buyers considering Brockville, Prescott, Athens, and other communities within the participating service area may want to investigate this.
Applicants should confirm current household income limits, permitted property values, and funding availability before relying on the program.
As with other municipally administered home buyer programs, confirm eligibility and funding before making an offer.
The Leeds & Grenville Homeownership Program provides application information and contact details.
Hastings County Down Payment Assistance
Hastings County offers a Home Ownership Down Payment Assistance Program to help eligible households buy properties within its service area.
Published program materials describe assistance of up to 10% of the purchase price, up to a maximum of $30,000, subject to income, purchase-price, residency, and other requirements.
This may interest purchasers considering Belleville, Quinte West, and qualifying nearby communities.
Applications have been closed under the latest program information reviewed for this article. Buyers should contact Hastings County to confirm whether additional funding becomes available.
Lennox & Addington County
Purchasers looking at Greater Napanee, Amherstview, Bath, or nearby communities can still investigate the federal and provincial programs discussed earlier.
However, locally administered down payment assistance does not automatically extend across municipal or county boundaries.
Prince Edward-Lennox and Addington Social Services (PELASS) is a good contact for information on current or future local assistance.
Check the administering municipality and eligibility rules before making plans around a particular program.
Can Home Buyer Programs Help You Purchase a Fixer-Upper?
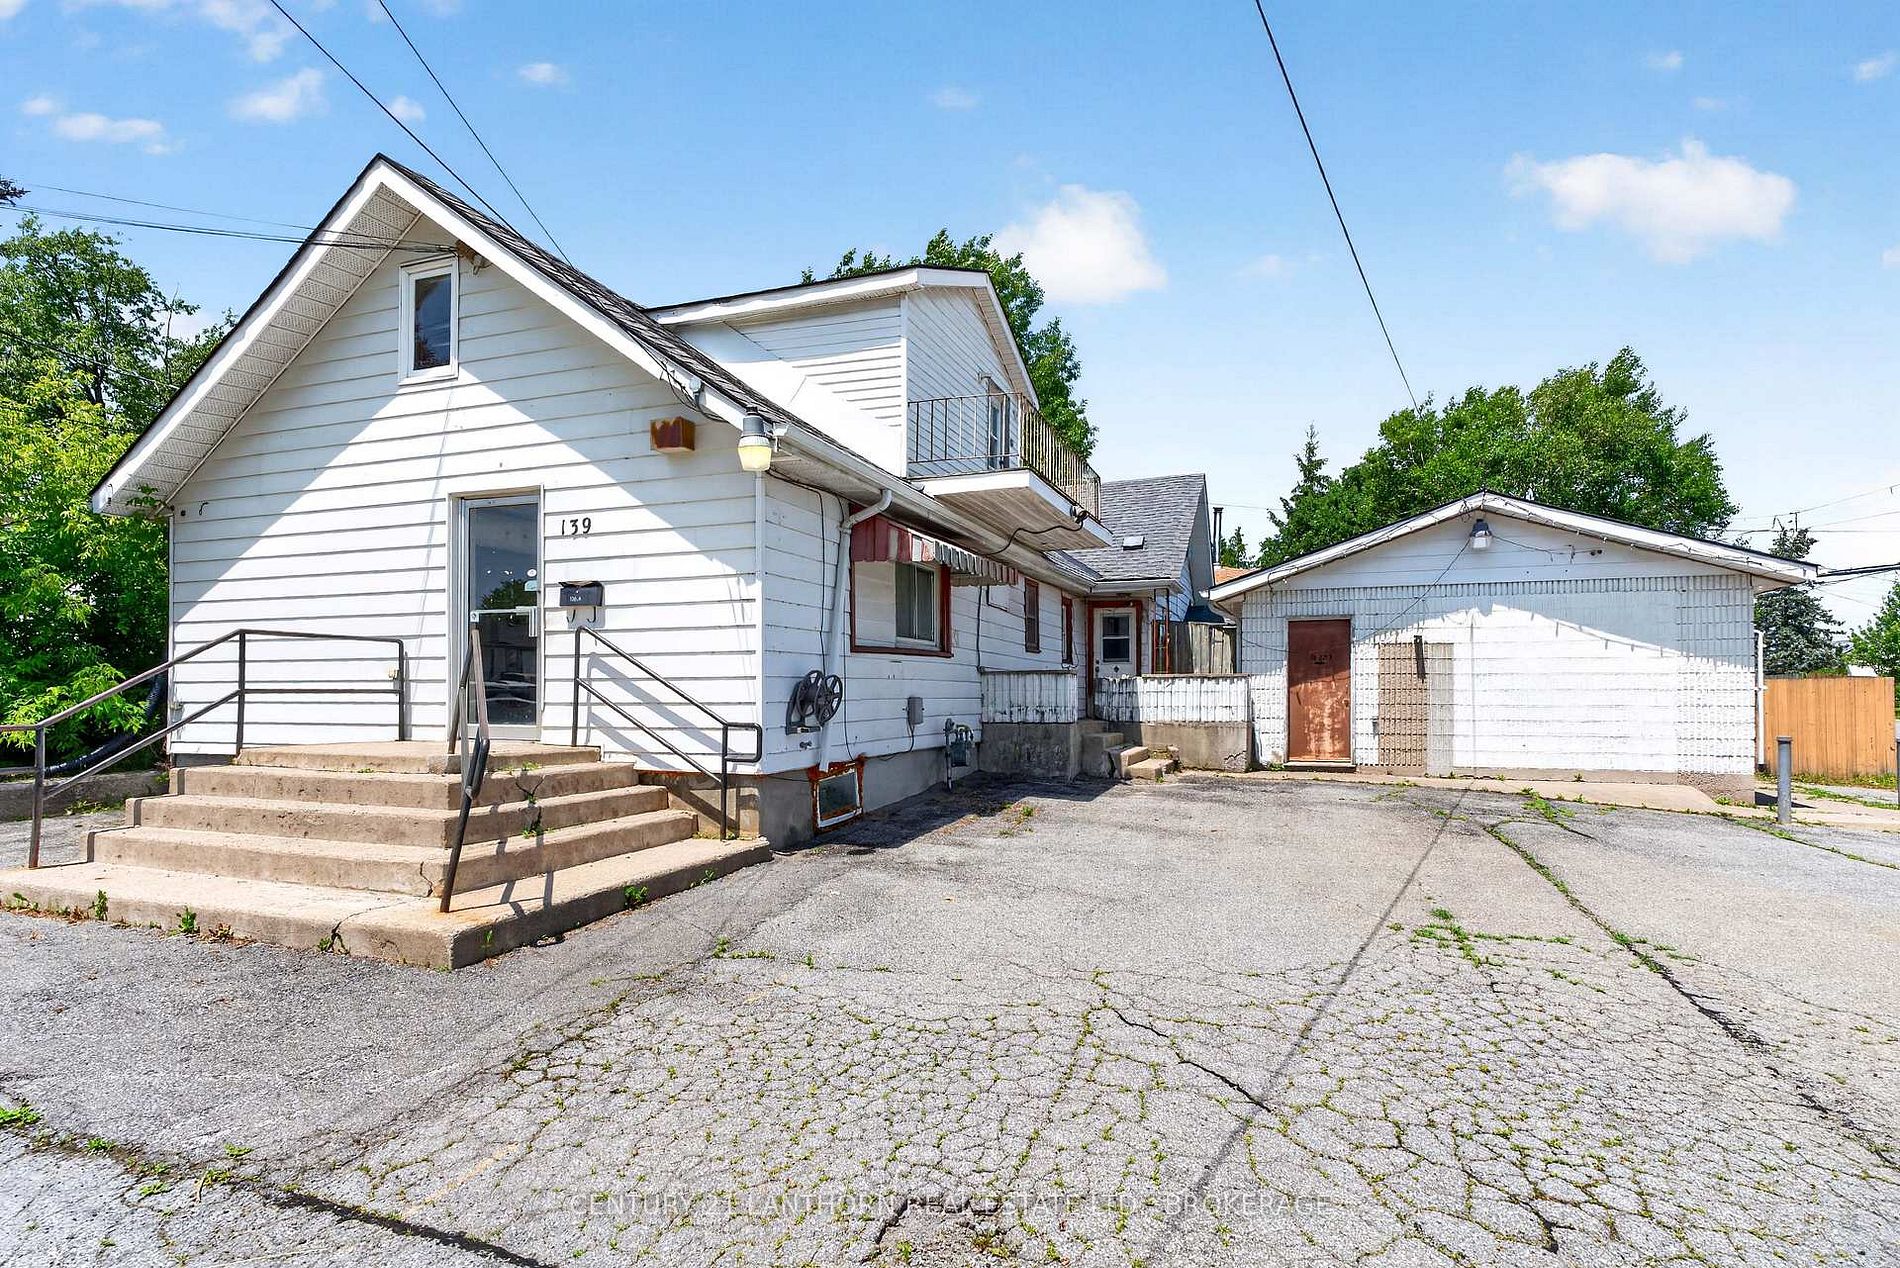
For many buyers in Kingston and surrounding communities, buying an older home that needs improvements may offer a more accessible entry point to the market.
Many home buyer programs can help buyers of older properties, so it’s worth exploring financial assistance before dismissing a home that needs cosmetic improvements.
Sometimes, sellers price homes with dated kitchens, older bathrooms, worn flooring, or decor that no longer appeals to today’s buyers below fully updated comparable homes.
For buyers willing to improve gradually, a manageable fixer-upper may be worth considering.
Most of the savings and tax benefits discussed in this article can apply to qualifying resale properties that need work.
You may still be eligible for FHSA withdrawals, the RRSP Home Buyers’ Plan, Ontario’s land transfer tax refund, and the federal Home Buyers’ Amount.
But the difference between cosmetic updates and major repairs matters.
Cosmetic Improvements Versus Major Repairs
You can often replace flooring, paint walls, update light fixtures, or refresh kitchen cabinets gradually as your budget allows.
Serious foundation problems, major water damage, unsafe electrical systems, failing roofing, or extensive plumbing problems present a different financial challenge.
A lower purchase price doesn’t automatically mean a bargain if you need significant repairs right away.
A professional home inspection is especially valuable when considering an older property.
Your lender and insurance provider will also need to be satisfied with the property’s condition. Homes with serious defects or habitability concerns may be more difficult to finance or insure.
Renovation Financing Through CMHC Improvement
Buyers considering a home that needs work may explore CMHC Improvement renovation financing.
This insured mortgage financing option lets you include qualifying property improvements in the mortgage.
With lender approval, purchasers may finance eligible renovation costs alongside the purchase.
The lender may require detailed estimates, documentation, and an assessment of the home’s expected value after improvements. Understand when renovation funds become available and whether you must pay contractors before receiving them.
You must ultimately repay the borrowed money as part of the financing.
Buyers using Kingston’s Home Ownership Program must meet the City’s inspection and eligibility requirements. The program also restricts combining its assistance with Kingston-Frontenac Renovates.
The objective isn’t simply to find the cheapest available property. It’s to buy a home that stays affordable after accounting for necessary repairs and future maintenance.
Affordable Neighbourhoods and Property Choices
Finding an affordable first home involves more than identifying the lowest asking price.
Location, property type, age, condition, and ongoing expenses all affect whether a home stays financially manageable.
In Kingston, parts of Kingscourt and Rideau Heights can offer more accessible options, particularly smaller detached homes and older properties.
Some established West End neighbourhoods may also offer options for buyers willing to consider homes that haven’t undergone extensive renovations.
Townhouses and condominiums offer additional options, but buyers should consider condo fees and potential special assessments.
Buyers may also explore communities outside Kingston, including Greater Napanee, Gananoque, Amherstview, Harrowsmith, and Verona.
However, a lower purchase price outside the City doesn’t mean lower overall living costs.
Commuting, heating, utilities, property taxes, and maintenance can substantially affect affordability.
For example, a rural property with a private well, septic system, and propane heating may have different operating expenses from a similarly priced home within Kingston.
Combining knowledge of local property values with available home buyer programs can help purchasers identify realistic opportunities within their budget.
What About New Construction HST Rebates?
Although many local first-time buyers will focus on resale properties, it’s worth briefly mentioning government tax relief for eligible new construction.
The federal First-Time Home Buyers’ GST/HST Rebate can reduce the federal portion of HST on qualifying new homes by up to $50,000.
Ontario also offers enhanced provincial new-housing relief and a temporary New Home Affordability Payment. Combined relief can reach $130,000 for eligible new or substantially renovated homes.
However, the programs have specific purchase-date, construction, property-value, occupancy, and other requirements.
They rarely apply to an ordinary resale home simply because it needs repairs.
Buyers considering new construction should review the CRA’s first-time home buyer GST/HST rebate information and Ontario’s New Home Affordability Payment.
It’s also important to establish whether the builder’s advertised price already reflects available rebates.
How Home Buyer Programs Can Work Together
Purchasers can combine several benefits if they meet each program’s eligibility requirements.
Consider a qualifying buyer purchasing an existing home in Kingston for $450,000.
For an eligible purchaser using standard minimum-down-payment financing, the down payment would be $22,500.
The buyer might have accumulated that amount through an FHSA or might combine FHSA savings with funds withdrawn through the RRSP Home Buyers’ Plan.
The regular provincial land transfer tax would be $5,475. If the purchaser receives the maximum $4,000 first-time buyer refund, the amount payable would fall to $1,475.
After completing the purchase, the buyer might also qualify for the federal Home Buyers’ Amount when filing an income tax return.
If the property needs improvements, the buyer could explore approved renovation financing before making an offer.
Municipal assistance may also be an option when funding is available, provided the buyer gets the necessary approval and meets income, asset, property, and lender requirements.
However, these programs provide different forms of assistance.
FHSA and HBP withdrawals let you access your own savings. Tax refunds and credits reduce your tax bill. Municipal forgivable loans come with specific conditions, while renovation financing requires additional borrowing.
Understanding these distinctions is essential to calculating how much assistance you actually qualify for.
Don’t Forget the Other Costs of Buying a Home
Saving the down payment is only part of preparing financially for homeownership.
Buyers should also budget for legal fees, title insurance, property tax adjustments, professional inspections, moving expenses, and other closing costs.
Where the down payment is below 20%, mortgage default insurance is required, subject to lender and insurer conditions. Ontario sales tax on the insurance premium is payable separately.
Once you’ve moved in, you’ll be responsible for property taxes, heating, electricity, water, home insurance, and maintenance.
Condominium purchasers must also consider monthly fees and potential special assessments.
A mortgage pre-approval is an important first step, but the maximum amount a lender will provide isn’t necessarily what you should spend.
A comfortable housing budget should allow room for unexpected repairs, savings, and everyday expenses.
Frequently Asked Questions About Home Buyer Programs
Can I qualify if I’ve owned a home before?
Possibly. Some federal programs allow former homeowners to qualify again after meeting specific ownership and occupancy requirements. Ontario’s land transfer tax refund has stricter rules.
Can I use my FHSA and RRSP Home Buyers’ Plan together?
Yes. Eligible buyers can use qualifying withdrawals from both programs toward the same property, as long as they meet each program’s conditions.
Do home buyer programs apply to fixer-uppers?
Yes. Most principal savings and tax benefits apply to qualifying resale homes that need improvements. However, mortgage, insurance, occupancy, and municipal program requirements still apply.
Can I apply for Kingston’s down payment assistance after making an offer?
No. Under the City’s published rules, applicants must obtain program approval before making an offer on a property.
Does Kingston’s Home Ownership Program need to be repaid?
The assistance is a forgivable loan with a 20-year term. You may need to repay it if you sell or transfer the home, or if it no longer meets the program’s conditions, before the loan is forgiven.
Can these programs be used to buy a condominium?
Many programs allow qualifying condominium purchases. Buyers should also review condominium fees, reserve fund information, and the possibility of special assessments.
Can I buy a home outside Kingston and still qualify for assistance?
Federal and Ontario benefits may apply to qualifying properties throughout the province. Municipal programs have specific service areas and eligibility rules, so you must check local assistance separately.
Are the new-home HST rebates available on ordinary resale homes?
Most previously occupied residential resale homes are exempt from HST. The new housing rebates apply to qualifying new or substantially renovated properties.
Is the old CMHC First-Time Home Buyer Incentive still available?
No. The former federal shared-equity First-Time Home Buyer Incentive stopped accepting new applications in March 2024. Don’t confuse it with current savings plans, tax benefits, or new housing rebates.
Don’t Miss These Guides
Understanding the available financial assistance is only one part of preparing for homeownership. These additional resources on KingstonRealty.org can help you navigate the buying process, evaluate properties, and make informed decisions.
Understanding Your Home Buying Process
A step-by-step guide to purchasing a property, from preparing your finances and obtaining mortgage pre-approval to viewing homes, making an offer, arranging inspections, and preparing for closing day.
Affordable Kingston-Area Neighbourhoods to Consider
Explore Kingston neighbourhoods and surrounding communities where buyers may find better value, along with the property types, commuting considerations, and expenses that affect affordability.
Kingston and Area Home Buyers Guidebook
A comprehensive resource covering the decisions involved in purchasing a home, including planning, financing, property selection, professional advice, and closing.
8 Hidden Costs of Buying a Home in Ontario
Learn about the expenses beyond your down payment, including legal fees, inspections, insurance, land transfer tax, moving costs, and future maintenance.
Home Inspections: Proven Ways to Protect Your Ideal Kingston Home
Learn what a professional inspection covers, why it matters when buying an older property, and how the findings can help protect your investment.
Making the Most of Home Buyer Programs in Ontario
Purchasing your first property is a major financial decision, and understanding the available home buyer programs can help make the process more manageable.
Start by reviewing your savings, setting a realistic budget, discussing financing with a qualified lender or mortgage broker, and exploring which assistance programs you may qualify for.
Many buyers in Kingston and Eastern Ontario may find an established detached property, townhouse, condominium, or manageable fixer-upper a better first home than a newly constructed house.
The right property isn’t necessarily the newest or most expensive home a lender will approve. It meets your needs, suits your lifestyle, and remains affordable after closing.
If you’re preparing to buy your first home in Kingston, Frontenac County, Lennox & Addington, or Leeds & Grenville, I’d be happy to help you understand the local market, explore available properties, and navigate the buying process.
With 14 years of experience helping buyers and sellers throughout Kingston and Eastern Ontario, I understand the importance of making informed decisions at every stage of a real estate transaction.
Helping Buyers Move In & Sellers Move On.
This article reflects program information published and reviewed in October 2026. Eligibility requirements, funding limits, application periods, and tax rules may change. Confirm current details with the relevant government agency, lender, financial adviser, or real estate lawyer before making a financial commitment.